01
Measured once, at the worst possible moment
A policy is priced on a single day of evidence, usually the day you applied, and then never measured again for the life of the cover.
In development
Neo Insurance is being built on one idea. If a person's blood work is measured every few months, and it is getting better, that should be worth something. Today no insurer on earth can see that change, so nobody is paid for it.
Neo Insurance is in development. No cover is available for purchase.
The whole tree
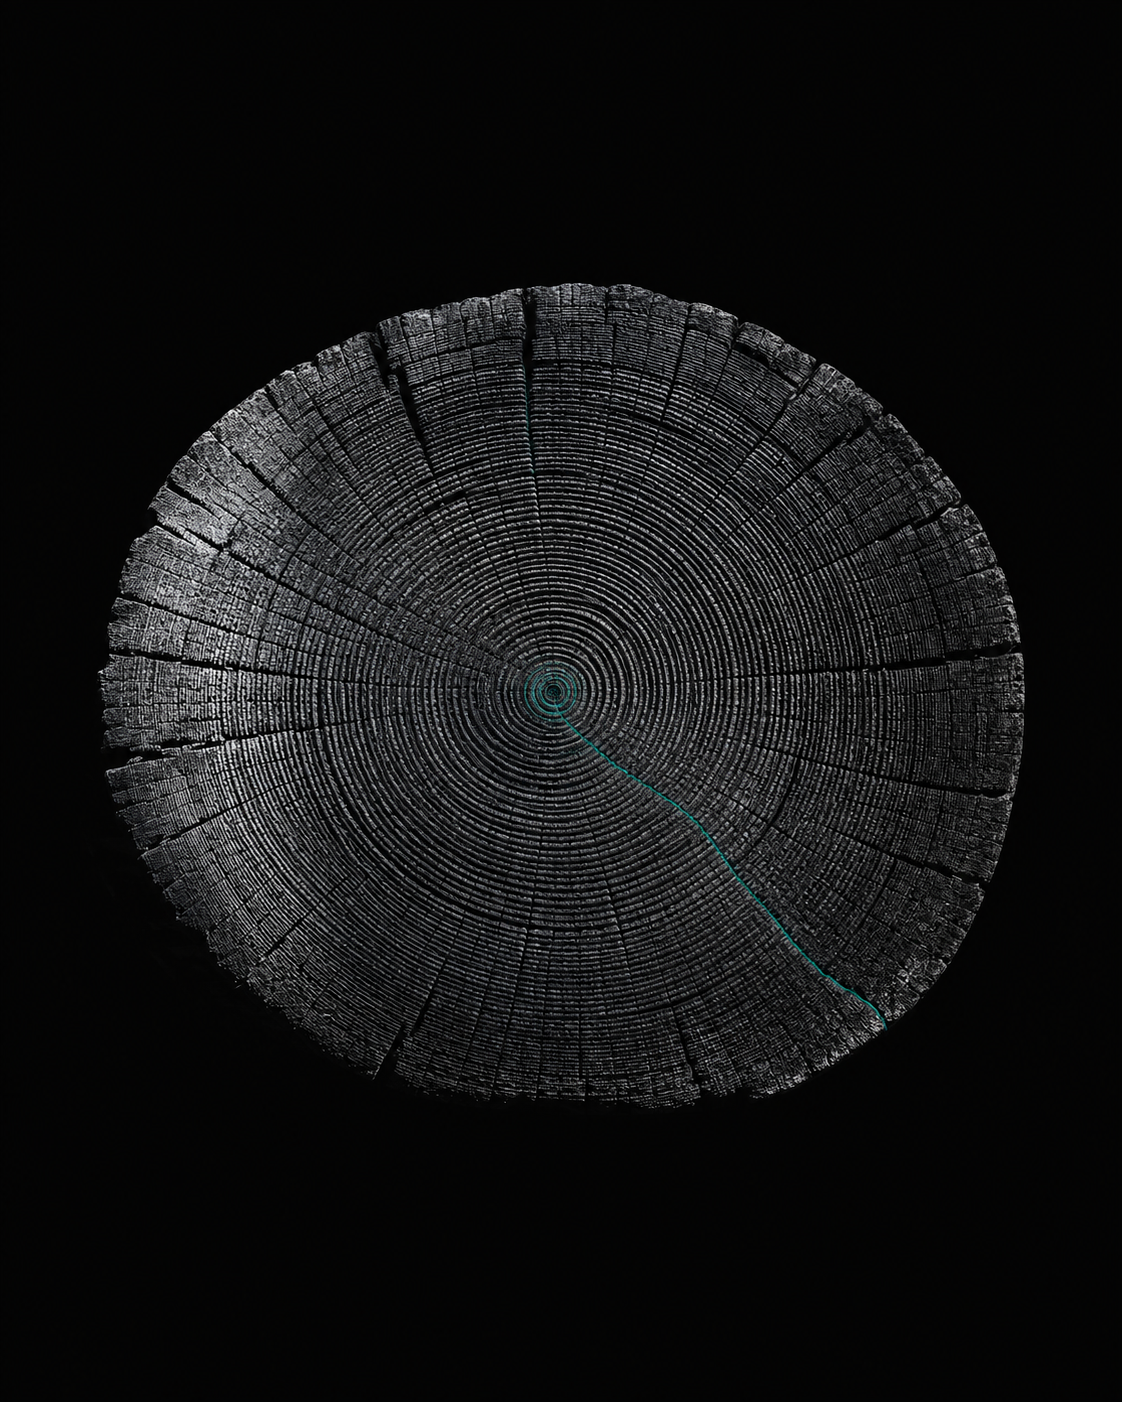
One ring is one year.
An underwriter has only ever seen one of them. The day you applied.
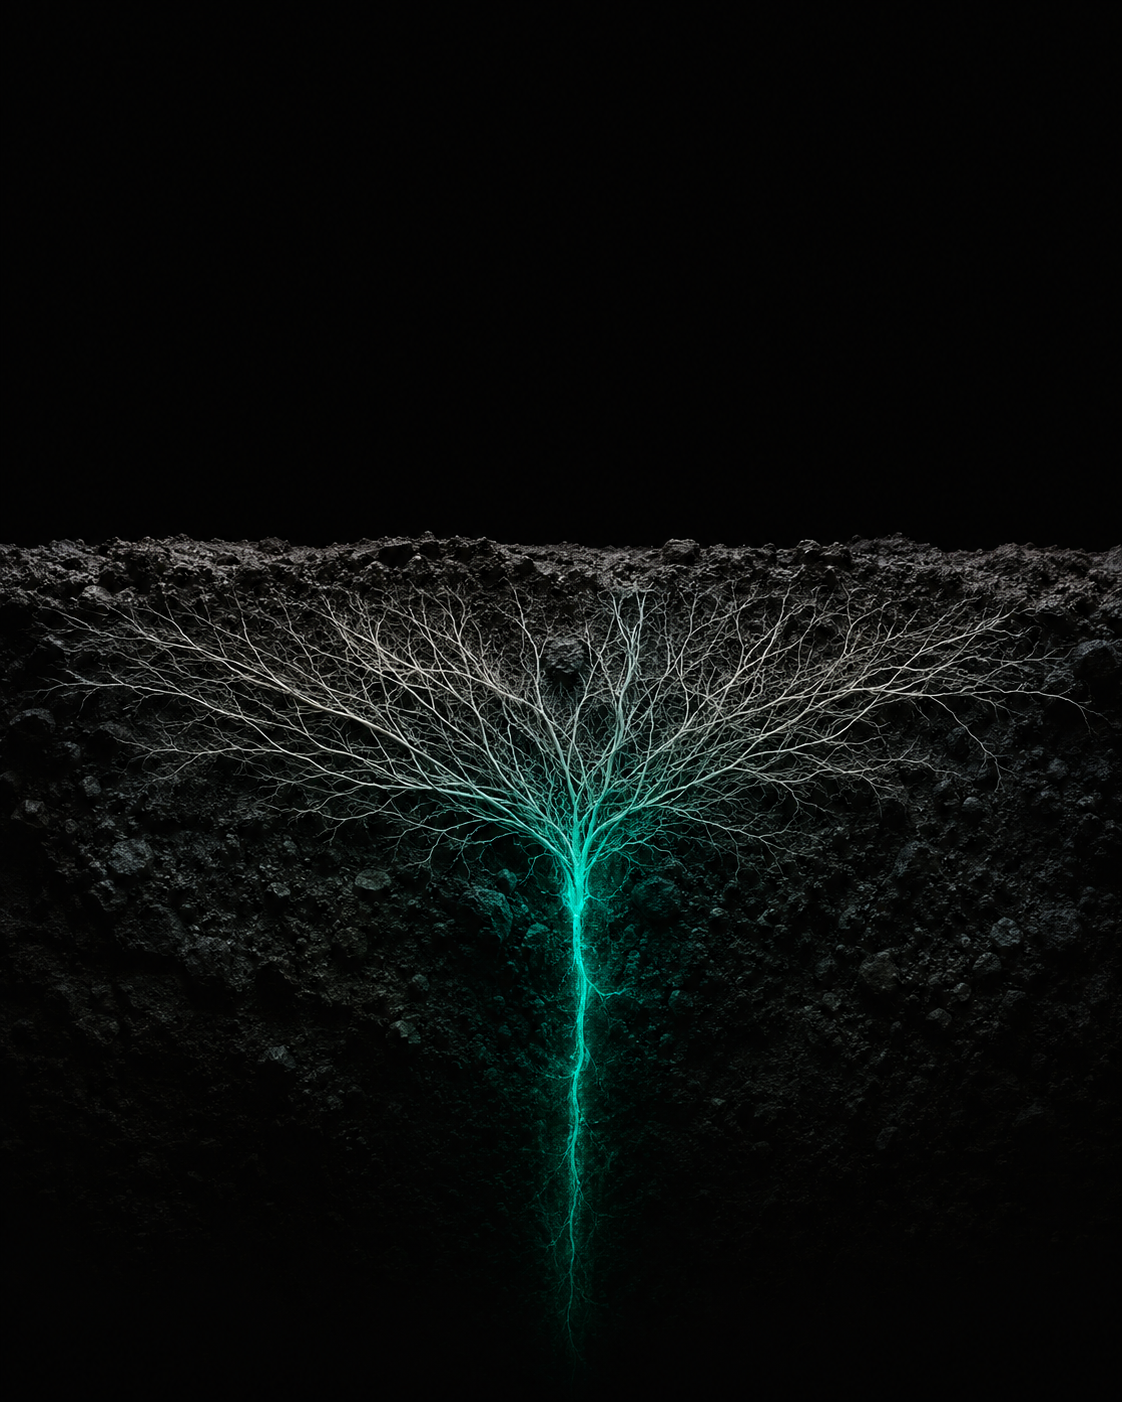
Half the tree is underground.
That is where the cause lives, and it is the half nobody has ever priced.
Risk should be priced all the way through the tree.Down to the root.
01
A policy is priced on a single day of evidence, usually the day you applied, and then never measured again for the life of the cover.
02
Reverse your own metabolic disease and no insurer will ever know. You pay exactly what the person who did nothing pays.
03
The first time anyone finds out something went wrong is the moment it has already gone wrong. That is a measurement failure, not a pricing failure.
We are building the version where all three of those are no longer true.
The gap
How cover works today
Priced on age, sex, height, weight and a form filled in once. Never measured again. Improvement is invisible to the insurer. Deterioration arrives as a claim. One contact a year, at renewal.
What we are building
Read against years of evidence the member already holds. A score that moves with every new panel. Improvement the insurer can see, at defined intervals and only with consent. Contact every week, because the member is already there for their own health.
The Neo HealthTruth Score
HealthTruth
863
out of 1000
Good
An example from a live Neo Root account. Neo gives educational guidance, not medical advice.
One number across the seven systems of root cause health, tracked over time and owned by the member. A blood panel is twenty numbers nobody can hold in their head. A score is one they can.
Risk today is priced on a form filled in once. A person can reverse their insulin resistance, halve their inflammation and add years to their life, and nothing about how they are rated moves. The intent is that a score which moves is recognised, at defined intervals, and only with the member's consent.
See the score on a live account at neoroot.aiWhat it is intended to cover
Consultations with a clinician from the Neo Doc network at neodr.ai, delivered remotely wherever remote consultation is permitted. A reading only becomes a change when someone acts on it.
neodr.aiPlannedScheduled panels at defined intervals, drawn locally, read by Neo and reviewed by a clinician. The panel is what builds the record.
PlannedSensors on a defined schedule, read continuously alongside the panel history. Glucose is the marker that answers within days rather than months.
PlannedIntended protection for hospitalisation, surgery and the critical conditions the root cause markers speak to.
PlannedThe first three are what make the fourth cheaper to provide.
What a member would see is one card, one record and one relationship, rather than four separate purchases. The member would deal with Neo, and Neo would deal with the laboratory, the sensor supply, the clinician and the carrier.
Global
The countries carrying the heaviest burden of metabolic disease are the countries with the thinnest private cover. A planned product that only works where insurance is already mature is a product aimed away from the problem. Neo Insurance is being designed to work in India, Brazil, Mexico and Southeast Asia as seriously as it works in the United States.
International Diabetes Federation Diabetes Atlas, adults aged 20 to 79.
Neo does not carry the risk and does not intend to become the risk carrier. In each market a licensed carrier would underwrite, while Neo would supply the platform, the record, the clinical network and the members.
The record, the scoring method, the clinical protocols and the member experience would be the same in every market. The carrier, the laboratory network, the sensor supply and the local terms are local, and always will be.
The promise
Nothing reaches an insurer unless the member chooses to share it, for a stated purpose, and the member can withdraw it.
Permission is granted purpose by purpose rather than as one blanket agreement, and a member who declines keeps the platform in full.
Genetic data is captured for the member, never scored, and blocked from export to any insurer or employer.
Neo is not a licensed insurer. Any planned cover would be underwritten by a licensed carrier in the member's own market.
The platform is the member's, and it stays useful whether or not they ever take cover.
Neo takes no pharmaceutical funding, for research, for content or for the clinical bench, and it addresses the root cause rather than promising to fix anyone.
What is not settled yet
No part of this has been filed, priced or approved by any regulator in any market.
No carrier has agreed to underwrite any of this anywhere. One carrier, in one market, for one product, is the first step.
It has never been scored against a population with known outcomes, so it is a stratification instrument rather than a pricing instrument.
Neo Doc is planned for early 2027, and it has to ship before any planned membership could carry a consultation benefit.
Until those close, the only thing this page can do is let a person register interest.
Register interest
We will tell you when there is real news about Neo Insurance in your country, and nothing else.